How it works
- 1. Free roof inspection. We walk the roof, chalk every strike, and document with photos. No cost, no pressure.
- 2. Documentation. We can be there when your carrier's adjuster inspects to show every damaged area we documented. Anything missed is documented in writing for you.
- 3. Approval + rebuild. Once approved, we complete the repair or replacement under your policy. You pay your policy deductible.
When the first answer is wrong
Partial approvals and denials happen, a few slopes approved instead of the whole roof, a discontinued shingle treated as repairable, code items left off the estimate. We compare the adjuster's estimate with what we documented and give you the photos and written documentation to support a re-inspection request.
A note on deductibles
You're responsible for your deductible. A contractor who offers to "cover" or waive it is a red flag that can put your claim at risk. We never do.
What a roof claim actually includes
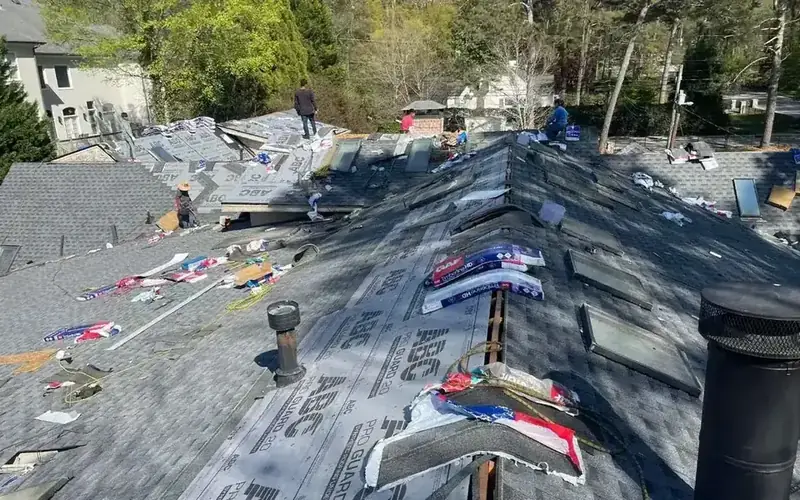
An insurance estimate is a list of line items, and missing lines are where homeowners lose money. A complete roof scope usually includes tear-off and disposal, underlayment, drip edge, ice-and-water protection, starter and ridge courses, step and counter flashing, pipe boots, vents, and any code-required upgrades - not just 'shingles by the square.'
We compare the carrier's estimate line by line against what your roof actually needs and what local building code requires. When something is missing, we document it with photos and measurements so you can share it with your insurer.
Your rights as a Georgia homeowner
- You choose your contractor. Your insurer can recommend one, but you're not required to use it.
- You're entitled to a copy of the adjuster's estimate and the reasons behind any denial.
- You can request a re-inspection if you believe damage was missed.
- Your deductible is your responsibility. Any contractor who offers to waive or 'cover' it is asking you to commit insurance fraud.
Mosaic is a roofing contractor, not a public adjuster or a law firm, and we can't negotiate your claim for you. What we do is give your insurer the clearest possible picture of your roof.
Recoverable depreciation, in plain English
Many policies pay in two checks. The first is the actual cash value - the replacement cost minus depreciation. The second, the recoverable depreciation, is released after the work is finished and the insurer receives the final invoice. We send that paperwork promptly so the second check isn't held up. If your mortgage company is named on the check, we'll help you through their endorsement process too.
Common reasons roof claims come up short
- Only the visibly damaged slopes are included, even though matching shingles aren't available.
- Code-required items like drip edge, ice-and-water protection or replacement of rotted decking are left out.
- Steep-pitch and high-roof labor charges are missing.
- Vents, pipe boots, flashing, gutters and other metal components aren't on the estimate.
- The roof was measured incorrectly or the waste factor is too low.
We document each of these with photos and measurements so you have the facts to share with your insurer. We keep it factual and professional.
Your rights under Georgia law
Georgia regulates residential roofing contractors under O.C.G.A. section 10-1-393.12 of the Fair Business Practices Act. Three rules matter most when your roof is covered by insurance.
- No negotiating on your behalf. A residential roofing contractor cannot represent or negotiate your insurance claim for roof repair or replacement, and cannot advertise that it will. Only a public adjuster licensed in Georgia, or an attorney, can do that for you.
- A five-day cancellation window. If your insurer tells you in writing that all or part of the claim is not covered, you can cancel a roofing contract paid through that policy before midnight of the fifth business day after you receive that notice. Cancel by written notice to the contractor's address on the contract.
- No payment before the window closes. A contractor cannot require payment from you until that five-day period has passed. The one exception is emergency work you acknowledge in writing is needed to prevent further damage.
Before you sign anything, ask any roofer to show you the cancellation notice that goes with the contract. A contractor who skips it, or who offers to handle the insurance company for you, is telling you something important.
The first 48 hours after a storm
- Stop further damage. If water is coming in, tarp or cover the opening and move belongings. Your policy expects you to prevent additional damage.
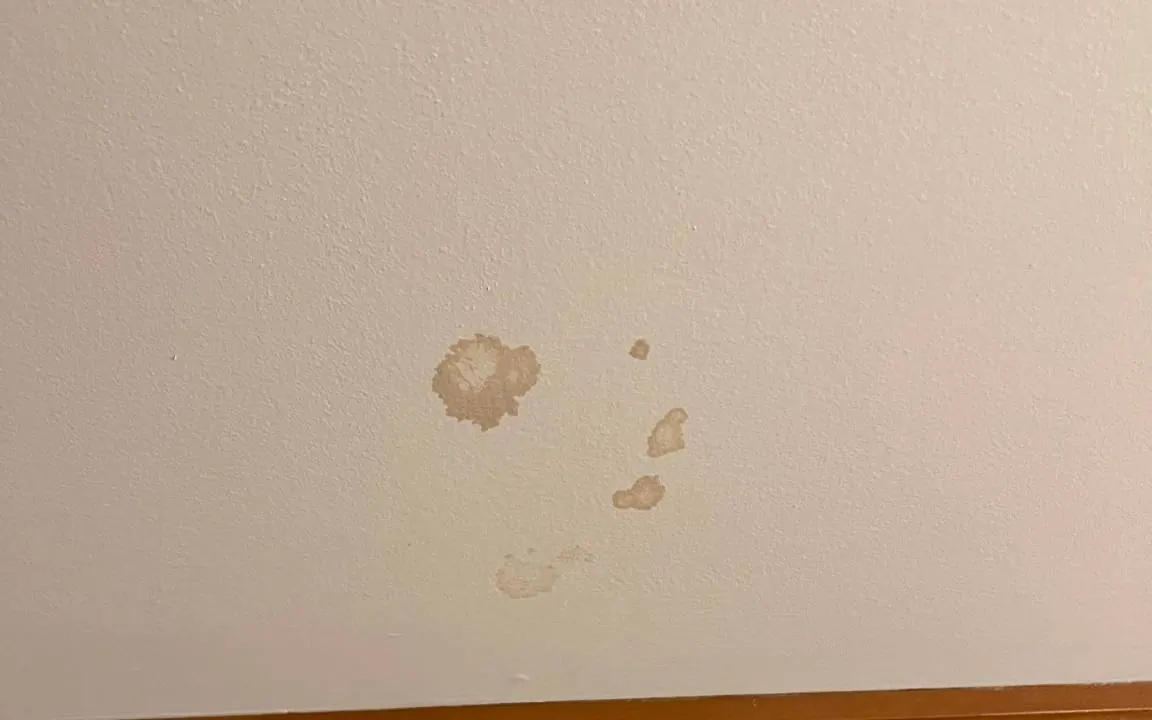
- Photograph everything before cleanup. Wide shots of each side of the house, close-ups of damage, and the interior ceilings and walls.
- Keep receipts for tarps, temporary repairs and hotel costs, since these are often part of the claim.
- Report the claim to your insurer and write down the claim number, the adjuster's name and when the inspection is scheduled.
- Get a free inspection from a roofer you choose, not one who comes to your door the day after the storm.
Why hail damage is so often missed
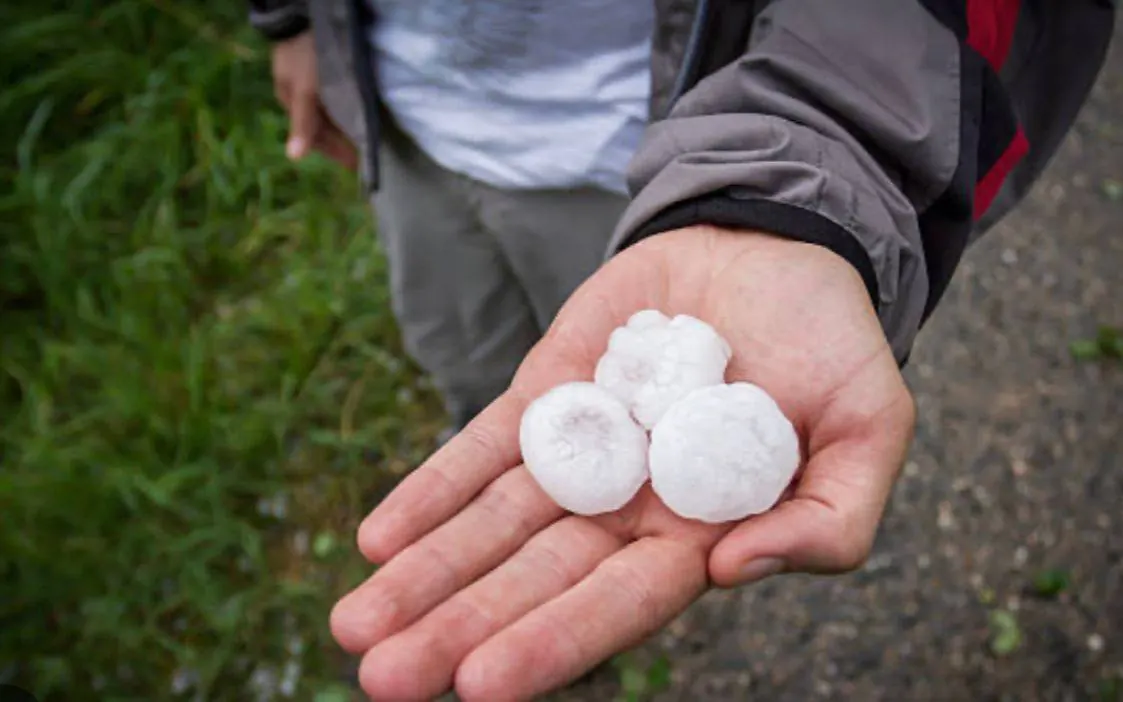
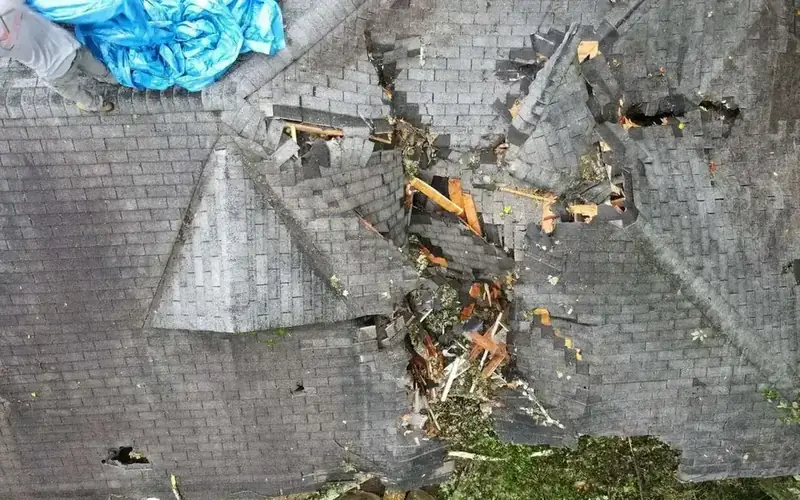
Hail damage is often hard to see from the ground and easy to miss in a quick look. On asphalt shingles, a hit usually shows as a bruise or a dark spot where the granules are knocked loose, sometimes with the mat underneath cracked or soft. Hail that is large enough to damage shingles is often large enough to dent soft metals, so we check gutters, downspouts, vents, flashing and the AC condenser fins as well.
The standard approach is a test square: a 10-by-10-foot area on each slope where we count the hits and document them. That count, with photos and the hail size estimate from the storm date, is what lets the adjuster see the damage the way the roof shows it.
Depreciation, supplements and what your policy actually pays
Most homeowner policies pay on one of two bases. Actual cash value (ACV) pays replacement cost minus depreciation for the roof's age and condition. Replacement cost value (RCV) pays the full cost of a like-kind repair, but often holds back the depreciated amount until the work is completed and documented. Your declarations page shows which one you have.
A supplement is a request to add items that were not in the first estimate, usually after work starts and the hidden damage shows up, such as rotted decking or code-required upgrades. Supplements go faster when the first documentation is complete, which is why we photograph everything before the first shingle comes off.
Frequently asked questions
Do I have to use the contractor my insurance company recommends?
No. In Georgia you choose your own contractor.
What if my claim was denied?
Call us. We'll inspect the roof and tell you honestly whether there's real storm damage worth contesting.
What do I pay?
On an approved claim, your deductible, plus any upgrades you choose that aren't part of the covered scope.
Should I call my insurance company or a roofer first?
Either works, but many homeowners call us first so they know whether there's real damage before opening a claim. Our inspection is free.
Can you be there when the adjuster inspects?
Yes. We can be there to show the adjuster every area of damage we documented. Negotiating the claim is between you and your insurer.
How long does the claim process take?
It varies by carrier and storm volume. Simple claims can be approved within a couple of weeks of the adjuster visit; claims that need a re-inspection take longer. We keep you updated at each step.
Do you charge anything to help with my claim?
No. Our inspection and claim documentation are free. If the claim is approved and you choose Mosaic to do the work, you pay your deductible plus any upgrades you pick.
Can a roofer file or negotiate my insurance claim for me?
No. In Georgia a residential roofing contractor cannot represent or negotiate your roof claim. Only a licensed public adjuster or an attorney can do that for you. We document the damage, meet the adjuster to show what we found, and give you written photos and notes.
My insurer says only part of the roof is covered. What now?
Ask for the estimate in writing and compare it line by line with the damage we documented. If something is missing, we put it in writing with photos so you can ask your insurer to re-inspect. You decide what to do next.
Can I cancel a roofing contract after my insurer denies the claim?
Under Georgia law, yes, within a set window. Before midnight of the fifth business day after you receive your insurer's written notice that all or part of the claim is not covered, you can cancel by written notice to the contractor's address on the contract. Keep a copy of your notice.